Is Certified Pre-Owned Financing Right for You?
Certified Pre-Owned Vehicle Financing Options
Certified pre-owned financing from Fort Myers Auto Group offers interest rates typically ranging from 1.99% to 6% on select models, significantly lower than standard used-car loans. Certified Pre-Owned Vehicle Financing Options combine the reliability of late-model vehicles with new-car APR benefits, providing Southwest Florida buyers substantial savings over the loan term.
Shop New, Certified & Pre-Owned Vehicles
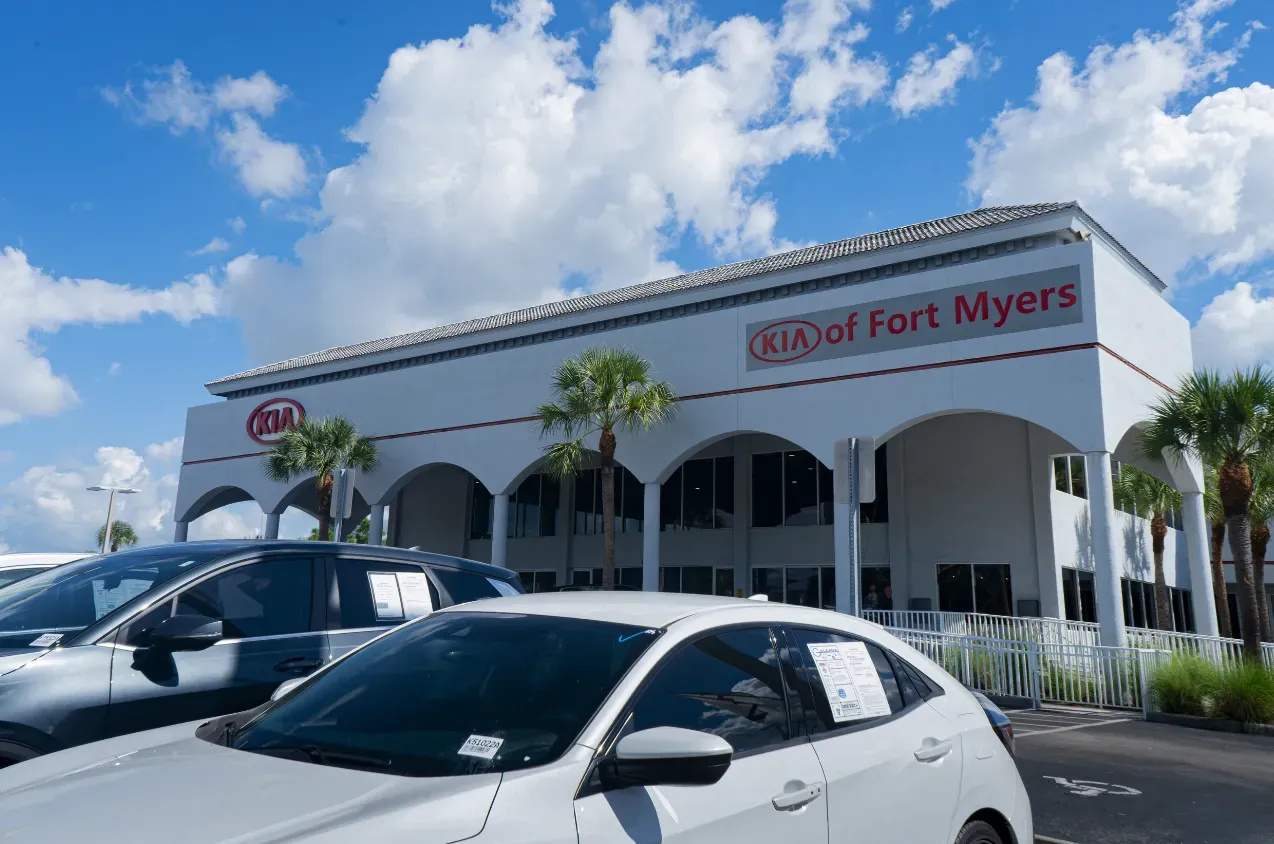
Browse inventory, book service, and apply for financing all in one place at Fort Myers Auto Group — home of CDJR of Fort Myers and Kia of Fort Myers, serving Fort Myers, Cape Coral, North Fort Myers, Lehigh Acres, Estero, and Bonita Springs, FL.
Key Takeaways
- Certified pre-owned financing interest rates range from 1.99% to 6% on select models, significantly lower than standard used-car loans.
- A manufacturer-backed warranty and multi-point inspection reduce lender risk, translating into lower interest rates for CPO buyers.
- Captive finance incentives from automakers offer promotional APRs that frequently sit below the national average for used car loans.
- CPO vehicles mitigate rapid initial depreciation because the original owner absorbed that early loss, preserving equity for the buyer.
What is a Certified Pre-Owned Vehicle?
A Certified Pre-Owned (CPO) vehicle is a late-model used car that has passed a rigorous manufacturer-backed inspection. Unlike a standard used car, a CPO model comes with an extended warranty and a detailed reconditioning report. Buyers who skip the CPO program risk absorbing repair costs that a factory warranty would have covered.
Fort Myers Auto Group offers a robust selection of Certified Pre-Owned vehicles. These models sit in a distinct category between new and traditional used inventory. The manufacturer sets strict eligibility criteria.
Age and mileage caps apply. A multi-point inspection conducted by factory-trained technicians is mandatory. Any component that fails the inspection is repaired or replaced with genuine parts before the vehicle earns the certification.
How does a CPO vehicle differ from a standard used car?
The difference centers on accountability. A standard used car is sold as-is unless a separate service contract is purchased. A CPO vehicle carries a warranty backed by the automaker, not a third party. This warranty often extends the original factory coverage. Roadside assistance and trip-interruption benefits are frequently included. The inspection report provides a documented history of the vehicle's condition at the time of sale, which a standard used car listing rarely offers.
Why do CPO programs lead to lower financing rates?
CPO programs reduce lender risk, which can lead to lower interest rates for buyers. Lenders view a manufacturer-backed warranty as a safeguard against mechanical failure. A vehicle with a verified condition report and remaining coverage represents a more secure asset. This reduced risk profile allows captive finance companies to offer Certified Pre-Owned Vehicle Financing Options with APRs that compete with new-car loans. A buyer who finances a non-certified used car often faces a higher rate because the lender assumes greater exposure to unexpected repair costs.
How Does CPO Financing Work?
Certified pre-owned financing pairs a factory-backed vehicle with manufacturer promotional rates. These rates often undercut standard used car loan pricing. A CPO vehicle carries a warranty and inspection, which lowers lender risk. Lower risk translates into better terms for the buyer.
Certified Pre-Owned Vehicle Financing Options fall into two main categories. Captive finance incentives come directly from automakers on their CPO models. Standard used car loans come from banks, credit unions, and private lenders. The difference matters. Manufacturer promotional APRs frequently sit below the national average for used car loans.
What Are Captive Finance Incentives on CPO Models?
Automakers offer promotional terms through their own finance arms. These captive incentives apply only to certified vehicles that pass factory inspection standards. The automaker absorbs part of the interest cost. That subsidy produces the lower APR a buyer sees on the contract.
How Does In-House Financing Compare?
In-house financing through a dealership simplifies the process. Fort Myers Auto Group offers a range of financing solutions to accommodate diverse customer needs and budgets. A buyer secures the loan directly through the dealership. Terms often carry more flexibility than a traditional bank route.
| Financing Path | Rate Source | Typical Advantage |
|---|---|---|
| Captive CPO incentive | Automaker finance arm | Promotional APR below standard used rates |
| In-house dealership | Dealer-arranged lender | Simplified process, flexible terms |
| External lender | Bank or credit union | Comparison baseline |
The right path depends on credit profile and vehicle selection. A CPO buyer should compare the captive offer against an in-house quote. Fort Myers Auto Group structures both options under one roof. That comparison happens without leaving the dealership.
What Are the Key Benefits of CPO Financing?
Certified Pre-Owned Vehicle Financing Options deliver three measurable advantages for Southwest Florida buyers. Lower interest rates, factory-backed warranty protections, and reduced depreciation exposure make CPO financing a financially disciplined alternative to both new-car loans and traditional used-car loans.
Why Do CPO Loans Carry Lower Interest Rates Than Standard Used Car Loans?
CPO programs receive manufacturer-backed rate incentives that standard used vehicles do not qualify for. Lenders view certified vehicles as lower-risk collateral because the automaker has inspected and reconditioned the unit. That reduced risk translates into lower interest rates compared to traditional used auto loans. Over a 60-month term, even a 1 to 2 percentage point rate reduction saves hundreds of dollars in total interest paid.
What Protections Come Standard With a CPO Vehicle?
Built-in factory-backed warranty protections are a standard feature of CPO programs. These warranties extend coverage beyond the original factory term and typically include roadside assistance. Fort Myers Auto Group's service centers provide vehicle care for CPO vehicles throughout the ownership period. A certified vehicle therefore carries both a manufacturer warranty and a local service network.
How Does CPO Financing Address Depreciation?
New vehicles lose a substantial portion of their value in the first two years. CPO vehicles mitigate rapid initial depreciation compared to new cars because the original owner absorbed that early loss. The buyer finances a vehicle whose value curve has already flattened. This preserves equity and reduces the risk of owing more than the vehicle is worth.
Fort Myers Auto Group structures CPO financing around transparent pricing and accessible financing. A streamlined trade-in process lets buyers apply existing vehicle equity toward the certified purchase. The result is a lower monthly payment, stronger warranty coverage, and a more predictable ownership cost.
What Are the Drawbacks of CPO Financing?
Certified pre-owned vehicle financing carries a higher purchase price than non-certified used models. The Certified Pre-Owned Vehicle Financing Options that deliver low promotional APRs also demand strong credit qualifications that not every buyer meets.
The CPO premium reflects the cost of rigorous inspections and extended warranty coverage. Buyers pay more upfront for that peace of mind. A comparable non-certified used car with similar mileage often lists for thousands less, which means financing a larger principal even when the interest rate is competitive.
Why Does CPO Inventory Limit Older Vehicle Choices?
Strict certification criteria restrict the age and mileage of vehicles that qualify. Most manufacturer programs cap eligibility at five or six model years and 60,000 to 80,000 miles. Shoppers seeking an affordable older truck or a budget-friendly sedan find far fewer options on a CPO lot. The selection skews toward recent trade-ins and off-lease returns, leaving budget-conscious buyers with a narrower pool.
Who Qualifies for the Lowest CPO Interest Rates?
Top promotional APRs require excellent credit. Fort Myers Auto Group notes that car loan rates in Southwest Florida vary by borrower credit, vehicle type, and market conditions. A buyer with a credit score below 700 may not access the headline promotional offers advertised nationally. Instead, that buyer faces rates closer to the average used-car range. The gap between the promotional rate and the approved rate erases much of the financing advantage that makes CPO appealing in the first place.
How Does CPO Compare to New Car Financing?
Certified pre-owned financing closes much of the gap between new and used loan rates. A CPO vehicle delivers near-new condition with interest costs that often beat standard used-car loans. Current new-car loan rates average a range, while used-car loans typically range higher. CPO promotional rates land between 1.99% and 6%, according to U.S. News. That spread means a CPO buyer can secure a lower APR than many new-car shoppers pay.
New-car loans generally carry lower interest rates than used-car loans. Depreciation and lender risk drive that difference. A new-car loan might sit at a lower rate, while a comparable used-car loan trends higher. CPO financing narrows the gap because automakers back certified vehicles with factory incentives. Fort Myers Auto Group helps Southwest Florida buyers compare these Certified Pre-Owned Vehicle Financing Options side by side.
| Factor | New Car | CPO Vehicle |
|---|---|---|
| Average APR | Varies by lender and credit profile | 1.99%–6% (promotional) |
| Initial depreciation | Steep in first 2–3 years | Already absorbed by first owner |
| Factory warranty | Full original term | Extended CPO coverage |
| Lender risk | Lower | Slightly higher, offset by certification |
Why Do CPO Rates Sometimes Beat New Car Rates?
Manufacturer CPO programs use subsidized financing to move certified inventory. U.S. News reports typical CPO interest rates from 1.99% to around 6% this November. Some extend to 7% or higher, but the low end undercuts many new-car offers. A buyer who qualifies for a low CPO APR pays less interest than a new-car borrower at a higher rate.
Does CPO Financing Offset Depreciation Losses?
CPO vehicles avoid the steep initial depreciation that hits new cars in the first two to three years. The first owner absorbs that loss. A CPO buyer finances a vehicle that has already stabilized in value. Lower principal plus a competitive APR reduces total interest paid over the loan term. Fort Myers Auto Group structures accessible financing so customers see the full cost before signing.
How Does CPO Compare to Standard Used Financing?
Certified Pre-Owned vehicle financing delivers substantially lower annual percentage rates than standard used car loans. Buyers who qualify for Certified Pre-Owned Vehicle Financing Options through manufacturer-backed programs avoid the elevated interest charges common with conventional bank or credit union used car lending.
The rate advantage is not marginal. U.S. News reports that CPO financing rates consistently beat the national average for used car loans from banks, credit unions, and other private lenders. That gap compounds across a 60-month or 72-month term, saving borrowers hundreds or even thousands of dollars over the life of the loan. Standard used car financing carries no such subsidy. Lenders price those loans against the vehicle's depreciated collateral value and the borrower's credit profile alone, producing APRs that routinely land 2 to 4 percentage points higher.
What Makes CPO Vehicles Cheaper to Own Over Time?
Total cost of ownership shifts in favor of CPO vehicles for two reasons. Lower financing costs reduce the monthly payment and the cumulative interest paid. At the same time, factory-backed warranty protections shrink out-of-pocket repair exposure. A standard used car purchase transfers nearly all post-sale mechanical risk to the buyer. A CPO purchase transfers much of that risk back to the manufacturer for the coverage period.
Fort Myers Auto Group supports this ownership model with fully certified technicians who service CPO vehicles to strict manufacturer standards. Maintaining warranty compliance requires documented, qualified service, and the dealership's certified staff ensures that requirement is met without third-party guesswork.
Why Do CPO Interest Rates Run Lower Than Standard Used Rates?
Automakers subsidize CPO financing to move late-model inventory and build brand loyalty. Banks and credit unions have no equivalent incentive. The manufacturer effectively buys down the rate, passing the savings to qualified buyers. Standard used car loans reflect raw market conditions with no such intervention, which explains the persistent spread between the two rate categories.
Does CPO Financing Require a Higher Credit Score?
Qualification thresholds for CPO financing mirror those for new-car promotional rates. Buyers with strong credit profiles access the lowest advertised APRs. Those with mid-tier credit may still qualify for rates below the standard used car average, though the exact terms depend on the lender and the specific certified program. Fort Myers Auto Group structures accessible financing pathways that match buyers to programs aligned with their credit standing, ensuring CPO incentives reach as many qualified applicants as possible.
How to Determine if CPO Financing Fits Your Budget?
Determining whether Certified Pre-Owned Vehicle Financing Options align with a household budget requires a methodical look at credit standing, total loan cost, and long-term ownership expenses. A low promotional APR loses its appeal if the monthly payment strains other financial obligations. Buyers who skip this analysis often overcommit, missing the very savings that make a CPO purchase attractive in the first place.
What Credit Score Is Needed for Promotional CPO Rates?
Reviewing a credit score is a critical first step in qualifying for promotional CPO APRs. Lenders reserve their lowest rates for borrowers with strong credit profiles. A score below the prime threshold does not disqualify a buyer, but it typically results in a higher APR that changes the monthly payment calculation. Fort Myers Auto Group offers a simple online credit application to streamline pre-approval, giving Southwest Florida shoppers a clear picture of their borrowing power before selecting a vehicle.
How Do You Calculate the True Cost of a CPO Loan?
Calculating the true long-term cost of ownership includes comparing APR, term, and total interest paid. A longer loan term lowers the monthly payment but increases the total interest over the life of the contract. Using an amortization table or online calculator translates the APR and term into a precise dollar figure, allowing buyers to compare scenarios side by side. This step prevents the common mistake of focusing solely on the monthly payment while ignoring the cumulative cost.
What Ongoing Costs Should Be Factored Beyond the Loan?
Evaluating warranty coverage and vehicle history reports helps assess long-term costs. A comprehensive CPO warranty reduces the risk of unexpected repair bills during the first years of ownership. Reviewing the vehicle history report confirms the car has not sustained damage that could lead to premature component failure. Together, these documents provide a clearer forecast of out-of-pocket expenses beyond the loan payment itself.
Where to Find CPO Financing in Fort Myers?
Certified pre-owned vehicle financing options in Fort Myers flow through two dedicated dealerships operated by Fort Myers Auto Group. CDJR of Fort Myers and Kia of Fort Myers both maintain finance departments staffed with specialists who structure loans for late-model certified vehicles. These teams work directly with a network of lenders to secure competitive terms for buyers across the region.
The group serves a broad geographic footprint. Customers from Cape Coral, Lehigh Acres, Naples, Estero, Bonita Springs, Punta Gorda, and Port Charlotte all access the same financing desk. That reach matters. A wider customer base gives the dealership leverage with banks and credit unions, which translates into rate options a smaller lot cannot match.
What makes dealership financing different from a bank loan?
Dealership financing specialists bundle the vehicle purchase and the loan into one transaction. This eliminates the back-and-forth between a bank loan officer and a sales desk. Fort Myers Auto Group's finance team pulls rates from multiple lenders simultaneously. The result is a single sitting where the buyer compares offers side by side rather than spending days chasing pre-approvals.
Does the dealership's ownership structure affect financing?
Yes. Fort Myers Auto Group is 100% privately owned. Independent ownership removes the rigid lending quotas and corporate rate floors that publicly traded dealer chains impose. The finance team adjusts deal structures case by case. A buyer with strong credit but a thin file often gets terms a formulaic system would reject. The company also directs profits back into Southwest Florida through local community events and charities, reinforcing relationships with regional lenders who value that local commitment.
Working with local dealership financing specialists helps secure competitive terms. The process starts with a credit application at either CDJR of Fort Myers or Kia of Fort Myers. From there, the finance manager matches the applicant to lender programs that favor certified pre-owned collateral. Those programs frequently carry subvented rates from the manufacturer, which banks cannot offer on a standard used-car loan.
FAQ
What interest rates does certified pre-owned financing offer?
Interest rates typically range from 1.99% to 6% on select models, significantly lower than standard used-car loans.
How does a CPO vehicle differ from a standard used car?
A CPO vehicle carries a warranty backed by the automaker, while a standard used car is sold as-is unless a separate service contract is purchased.
Why do CPO programs lead to lower financing rates?
CPO programs reduce lender risk because the manufacturer-backed warranty and multi-point inspection safeguard against mechanical failure, translating into lower interest rates.
Conclusion
Certified pre-owned financing delivers lower rates and reduced risk because the manufacturer-backed warranty and multi-point inspection protect the lender, a benefit standard used-car loans lack. Buyers who complete a credit application at either dealership location gain access to these subvented programs, making the next step a straightforward comparison of offers tailored to their credit standing and budget.
Our Fort Myers Showrooms
Fort Myers, FL 33912
Fort Myers, FL 33912