How to Secure the Best Car Loan Rates
Secure the Best Car Financing Options Near Me
Securing the best car loan rates requires a strong credit score, a substantial down payment, and preapproval from multiple lenders. Fort Myers Auto Group assists customers in Fort Myers and Southwest Florida by offering transparent financing options and in-house solutions. A higher credit score typically secures lower interest rates.
Shop New, Certified & Pre-Owned Vehicles
Browse inventory, book service, and apply for financing all in one place at Fort Myers Auto Group — home of CDJR of Fort Myers and Kia of Fort Myers, serving Fort Myers, Cape Coral, North Fort Myers, Lehigh Acres, Estero, and Bonita Springs, FL.
Key Takeaways
- A higher credit score typically secures lower interest rates and better loan terms.
- Rate shopping through preapproval from a bank or credit union establishes a baseline before visiting a dealership.
- A larger down payment reduces the lender's exposure and often secures better terms.
- Requesting free credit reports from AnnualCreditReport.com and disputing errors prevents rejected applications and higher monthly payments.
Why does your car loan rate matter?
A car loan rate determines the total cost of vehicle ownership over time. Even a small percentage difference adds thousands of dollars to the final purchase price.
Car Financing Options Near Me carry widely varying interest rates. Shoppers who accept the first offer without comparison risk overpaying significantly. Consumer Reports notes that a higher credit score typically leads to a lower interest rate, while lower scores trigger the opposite result. That spread between rates translates directly into monthly payment differences and total loan costs.
How much does a high rate actually cost?
Agreeing to a high-interest loan makes a car cost thousands more in the long run, according to Credit Union of Colorado. A buyer financing a vehicle at a higher rate instead of a lower one pays extra dollars across the loan term. The loss compounds with longer loan durations. Buyers stretching terms to longer periods amplify the penalty further.
What determines the rate a buyer receives?
Credit history stands as the primary factor. Lenders assess risk through credit scores and adjust rates accordingly. Down payment size also influences the offer. The vehicle itself matters too: new cars frequently qualify for lower rates than used models.
Fort Myers Auto Group offers a range of financing solutions to accommodate diverse customer needs and budgets. The company's accessible financing approach connects buyers with competitive rate options regardless of credit profile. As a 100% privately owned dealership group in Southwest Florida, Fort Myers Auto Group keeps lending decisions local. That structure eliminates the rigid rate policies common at distant corporate chains.
Rate shopping before visiting the dealership protects buyers from unnecessary expense. Preapproval from a bank or credit union establishes a baseline. The dealership's finance team then works to match or beat that rate. Our goal is to give you an interactive tour of our new and used inventory, as well as allow you to conveniently get a quote, schedule a service appointment, or apply for financing. A streamlined trade-in process further reduces the amount financed, lowering the principal that accrues interest.
What prerequisites do you need before starting?
Prospective buyers secure better financing terms by preparing before visiting any dealership. Fort Myers Auto Group serves eight communities across Southwest Florida, including Fort Myers, Cape Coral, Naples, Estero, Bonita Springs, Punta Gorda, Port Charlotte, and Lehigh Acres, making preparation essential for buyers throughout the region.
Credit health determines loan eligibility and interest rates. A higher score unlocks lower rates, while errors on a credit report block access to favorable terms. Credit Union of Colorado's auto loan guide recommends requesting free copies of credit reports from AnnualCreditReport.com and disputing any errors before visiting dealerships. This step prevents rejected applications and higher monthly payments that cost thousands over a loan's life.
Documentation readiness accelerates the financing process. Buyers who arrive without proof of income, residence, and insurance face delays that stall vehicle delivery. Fort Myers Auto Group's simple online credit application streamlines the car financing experience, allowing customers to submit information before stepping onto the lot.
What documents do lenders typically require?
Lenders request proof of income through recent pay stubs or tax returns. A valid driver's license and proof of residence, such as a utility bill, confirm identity and address. Current insurance information completes the standard documentation package.
How does vehicle selection affect financing preparation?
Choosing between new and used vehicles changes loan terms and down payment requirements. Fort Myers Auto Group maintains fully certified technicians and provides genuine OEM parts and accessories, ensuring every vehicle meets quality standards regardless of financing path.
Buyers who research inventory online before visiting save time and narrow their Car Financing Options Near Me to vehicles matching their budget.
Trade-in valuation adds another preparation layer. A streamlined trade-in process at Fort Myers Auto Group requires current vehicle condition details and title availability. Gathering this information beforehand eliminates surprises during appraisal.
How do you check and improve your credit score?
Checking a credit score starts with requesting free credit reports from AnnualCreditReport.com. A good score, based on a history of paying bills and debts, indicates to lenders that a borrower is more likely to pay on time and in full. Fort Myers Auto Group is committed to providing accurate information and exceptional service to its customers throughout this process.
What credit score do car lenders look for?
Lenders review credit scores to assess repayment risk before approving any car financing options near me. A higher score typically unlocks lower interest rates and better loan terms. Even modest credit improvements can unlock premium car financing offers that dealers advertise during peak buying periods.
How do you improve your credit score before applying?
Follow these steps in order to strengthen a credit profile before visiting a dealership:
- Request free copies of credit reports from AnnualCreditReport.com and review each entry for errors.
- Dispute any inaccurate late payments, collections, or account balances directly with the credit bureaus.
- Pay down outstanding credit card balances to reduce the credit utilization ratio.
- Make all current bill payments on time, since payment history carries significant weight.
- Avoid opening new credit accounts in the months before applying for an auto loan.
Fort Myers Auto Group supports local community events and charities, reflecting the company's commitment to the Southwest Florida region it serves. Prospective buyers who check and improve their credit scores before applying position themselves for stronger financing outcomes.
How do you determine your budget and loan structure?
Determining a budget starts with understanding the three principal financing structures available to car buyers. Traditional loans, leasing, and in-house financing each carry distinct repayment obligations and ownership outcomes. A buyer who skips this evaluation risks committing to monthly payments that strain household cash flow for years.
What are the main car financing options near me?
Three structures dominate the Southwest Florida market. Each suits a different financial profile and vehicle need.
- Traditional loans come from banks and credit unions. The lender provides a lump sum repaid over time with interest, typically at fixed or variable rates.
- Leasing allows a driver to use a vehicle for a set period while making monthly payments. At lease end, the lessee either purchases the vehicle or returns it.
- In-house financing through Fort Myers Auto Group secures a loan directly at the dealership. This route often carries more flexible terms than external lenders.
How does loan structure affect total cost?
Loan structure determines both monthly obligation and long-term ownership cost. A traditional loan builds equity with every payment, but interest accrues across the full term. Leasing lowers monthly payments because the lessee finances only the vehicle's depreciation during the lease period, not its full purchase price. In-house financing simplifies the process by consolidating vehicle selection and loan approval into one transaction at Fort Myers Auto Group.
| Structure | Payment Basis | Ownership Outcome |
|---|---|---|
| Traditional loan | Full vehicle price plus interest | Buyer owns after final payment |
| Leasing | Depreciation during lease term | Return or purchase at lease end |
| In-house financing | Negotiated at dealership | Buyer owns after final payment |
What budget factors should a buyer weigh first?
A buyer should calculate the maximum affordable monthly payment before visiting any dealership. That figure then narrows which structures remain viable. Fort Myers Auto Group maintains the best pricing and biggest discounts on new and pre-owned vehicles, which reduces the amount requiring financing. Lower principal means lower interest charges across the loan term.
How do you get pre-approved and shop lenders?
Pre-approval locks in a loan offer before a buyer visits the lot. Shopping multiple lenders protects against overpaying by thousands over the life of the loan. A single percentage point difference on a vehicle adds extra interest across a longer term. Buyers who skip this step lose negotiating leverage the moment they walk through the showroom door.
What documents are needed before applying?
Lenders require proof of income, proof of residence, and a government-issued ID. Recent pay stubs or tax returns establish income. A utility bill or lease agreement confirms the address. Having these documents ready before starting any application prevents delays that stall the purchase.
How many lenders should a buyer contact?
Three to five lenders provide enough comparison without overwhelming the applicant. Banks, credit unions, and online lenders often offer more competitive car financing than dealership options, according to the 9 Tips for Getting the Best Auto Loan Deal This Season guide. Rate shopping within a 14-day window minimizes credit score impact because multiple inquiries for the same loan type count as a single hard pull.
Fort Myers Auto Group simplifies the process with a simple online credit application designed to streamline the car financing experience. The application works at any stage of the car-buying journey, whether a buyer is just starting research or ready to finalize a deal. Submitting it early gives the dealership's finance team time to structure terms that match the applicant's profile.
The company offers a range of financing solutions to accommodate diverse customer needs and budgets. Traditional loans, lease agreements, and in-house financing all sit on the table. Buyers who arrive with a pre-approval from an outside lender gain a benchmark rate. That benchmark forces every offer to compete on real numbers rather than monthly payment estimates.
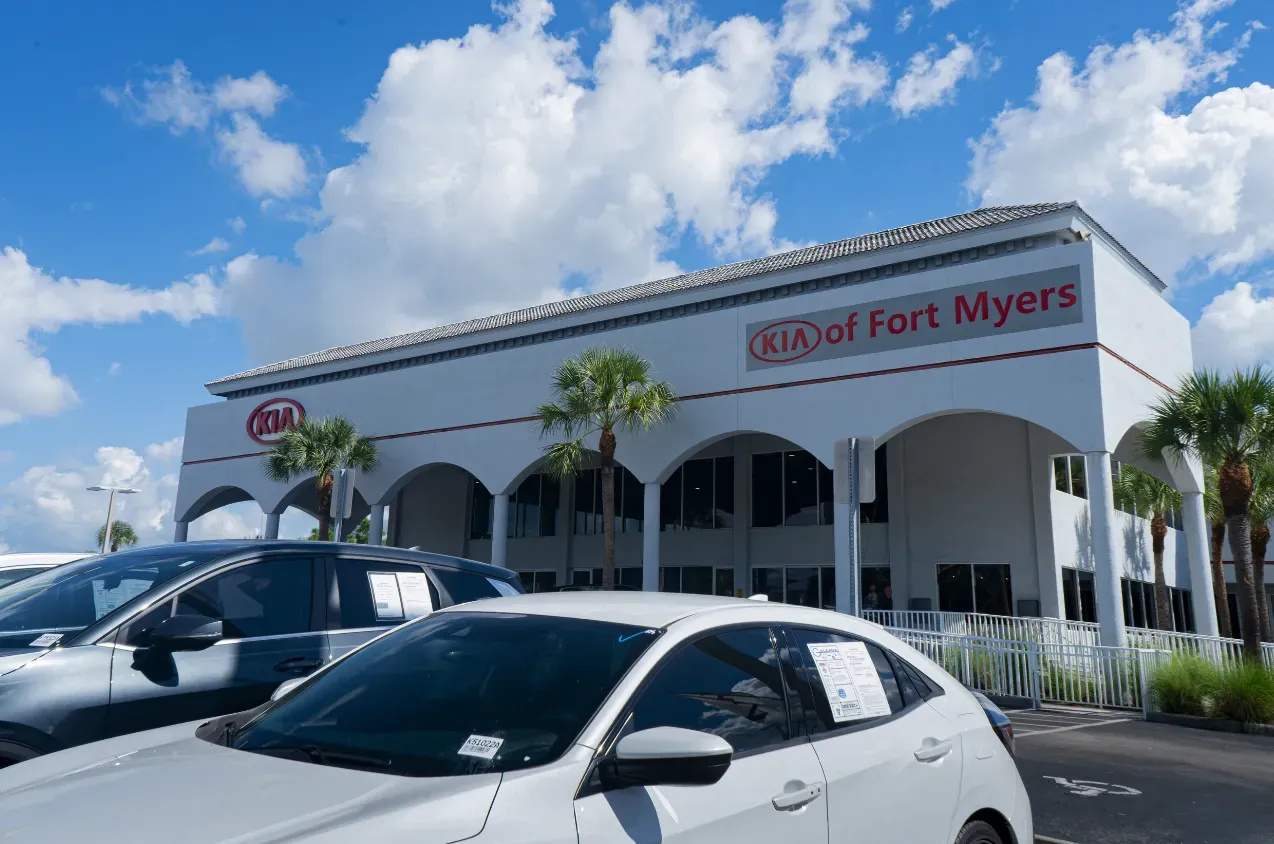
Fort Myers Auto Group operates two dealerships in Fort Myers, FL: CDJR of Fort Myers and Kia of Fort Myers. Both locations process financing applications for new and used inventory. A buyer searching for car financing options near me in Southwest Florida finds transparent pricing and accessible financing at either storefront. The streamlined trade-in process folds equity from a current vehicle directly into the new loan structure, reducing the amount financed.
How do you evaluate dealership financing options?
Evaluating dealership financing requires a systematic comparison of loan structures, terms, and total costs. Fort Myers Auto Group provides in-house financing that simplifies the approval process with more flexible terms than traditional bank loans. Shoppers who skip this evaluation often pay thousands more over the life of their loan.
What makes in-house financing different from bank loans?
In-house financing allows a buyer to secure a loan directly through the dealership. Fort Myers Auto Group structures these loans with terms that accommodate a wider range of credit profiles. The process eliminates the back-and-forth between a third-party lender and the sales desk. Decisions happen on-site, which shortens the time from application to approval.
How do certified pre-owned vehicles affect financing?
Certified Pre-Owned vehicles carry lower risk for lenders. Fort Myers Auto Group offers a robust selection of Certified Pre-Owned vehicles that have passed rigorous inspections. Lenders often assign better rates to CPO units because the vehicle's condition and warranty coverage reduce default risk. A buyer targeting a CPO model frequently qualifies for promotional rates unavailable on standard used cars.
Follow these steps to evaluate any dealership financing offer:
- Request the total financed amount. Confirm the figure matches the vehicle price plus taxes and fees, with no hidden add-ons.
- Compare the annual percentage rate across terms. A shorter-term loan costs less total interest than a longer-term loan, even if the longer term carries a lower rate.
- Verify prepayment penalties. Some contracts charge fees for paying off the loan early.
- Review the down payment requirement. A larger down payment reduces the principal and the total interest paid.
- Confirm service support after purchase. Fort Myers Auto Group's service centers provide vehicle care with fully certified technicians, which protects the investment over time.
A dealership that pairs financing with long-term service support delivers value beyond the loan itself. Fort Myers Auto Group supports local community events and charities, reflecting a business model built on lasting relationships rather than one-time transactions. Buyers who weigh these operational factors alongside the numbers on the contract make more informed decisions.
How do you review and finalize the loan terms?
Reviewing loan terms requires comparing total cost over the full term, not just the monthly payment. Fort Myers Auto Group is committed to providing accurate information and exceptional service throughout this process.
Before signing, a buyer should examine three specific elements in the contract. First, confirm the interest rate matches the quoted figure.
Second, verify the loan term length in months. Third, check for any prepayment penalties or hidden fees.
What should a buyer check before signing a car loan?
A buyer should verify the total amount financed equals the vehicle price plus taxes and fees, minus any down payment. The monthly payment must align with the agreed term and rate. Any discrepancy signals a need for clarification before finalizing.
How does mileage affect lease finalization?
Mileage limits apply to lease agreements and directly impact total cost. Exceeding the stated annual mileage triggers per-mile charges at lease end. Buyers comparing car financing options near me should weigh usage patterns against lease terms.
Fort Myers Auto Group has two dealerships: CDJR of Fort Myers and Kia of Fort Myers. Each location provides financing review support for customers finalizing purchase or lease documents.
The review process follows a clear sequence:
- Confirm the interest rate and annual percentage rate match the initial quote.
- Verify the loan term and total number of payments.
- Check mileage limits for lease contracts.
- Review flexibility provisions if credit or income circumstances change.
- Sign only after every figure matches the agreed terms.
Fort Myers Auto Group's Privacy Policy was last updated on January 1, 2020. Customers receive a copy of all finalized documents for their records.
What common mistakes should you avoid?
Avoiding costly financing errors protects buyers from paying thousands more over a loan's life. Agreeing to a high-interest loan makes a car cost thousands more in the long run. Fort Myers Auto Group helps customers sidestep these pitfalls through car financing options near me that prioritize clarity.
What happens when buyers skip rate comparisons?
Skipping rate comparisons leaves money on the table. A single percentage point difference compounds across a loan term. Fort Myers Auto Group presents multiple financing structures so customers see the full cost picture before signing.
How does overlooking OEM parts affect long-term ownership?
Overlooking genuine parts creates reliability risks. Fort Myers Auto Group's auto parts specialists provide genuine OEM parts and accessories. These components match factory specifications and protect vehicle performance.
Common mistakes to avoid include:
- Accepting the first loan offer without comparing annual percentage rates.
- Focusing only on monthly payments instead of total interest paid.
- Ignoring credit report errors before applying for financing.
- Skipping preapproval and losing negotiating leverage.
- Overlooking OEM parts when budgeting for maintenance.
Fort Myers Auto Group is 100% privately owned. That structure keeps financing decisions local and responsive. The company serves Fort Myers, Cape Coral, Lehigh Acres, Naples, Estero, Bonita Springs, Punta Gorda, and Port Charlotte. Buyers across these communities receive consistent guidance on loan terms and ownership costs.
FAQ
How can I get the best car loan rate before visiting a dealership?
A higher credit score, a substantial down payment, and preapproval from a bank or credit union establish a baseline for better terms.
What factors determine the car loan rate I receive?
Credit history is the primary factor, followed by down payment size and whether the vehicle is new or used.
How does Fort Myers Auto Group help me secure a competitive rate?
Fort Myers Auto Group offers transparent financing options and keeps lending decisions local as a 100% privately owned dealership, working to match or beat your preapproved rate.
Conclusion
Securing the best car loan rate requires a buyer to compare annual percentage rates, verify contract figures, and avoid common pitfalls like skipping preapproval. Fort Myers Auto Group supports this process with transparent financing options and local decision-making. A buyer who reviews total cost over the full term and confirms every figure before signing makes a sound financial decision.
Our Fort Myers Showrooms
Fort Myers, FL 33912
Fort Myers, FL 33912