Car Financing Options Available Near You
Car Financing Options Near Me in Fort Myers in Fort Myers, Florida
Fort Myers Auto Group offers flexible car financing options for buyers in Fort Myers, FL, including traditional loans and buy here pay here programs for those with credit challenges. Current new-car loan rates vary by lender and credit profile, while used-car loan rates also depend on these factors. The dealership serves eight Southwest Florida communities.
Shop New, Certified & Pre-Owned Vehicles
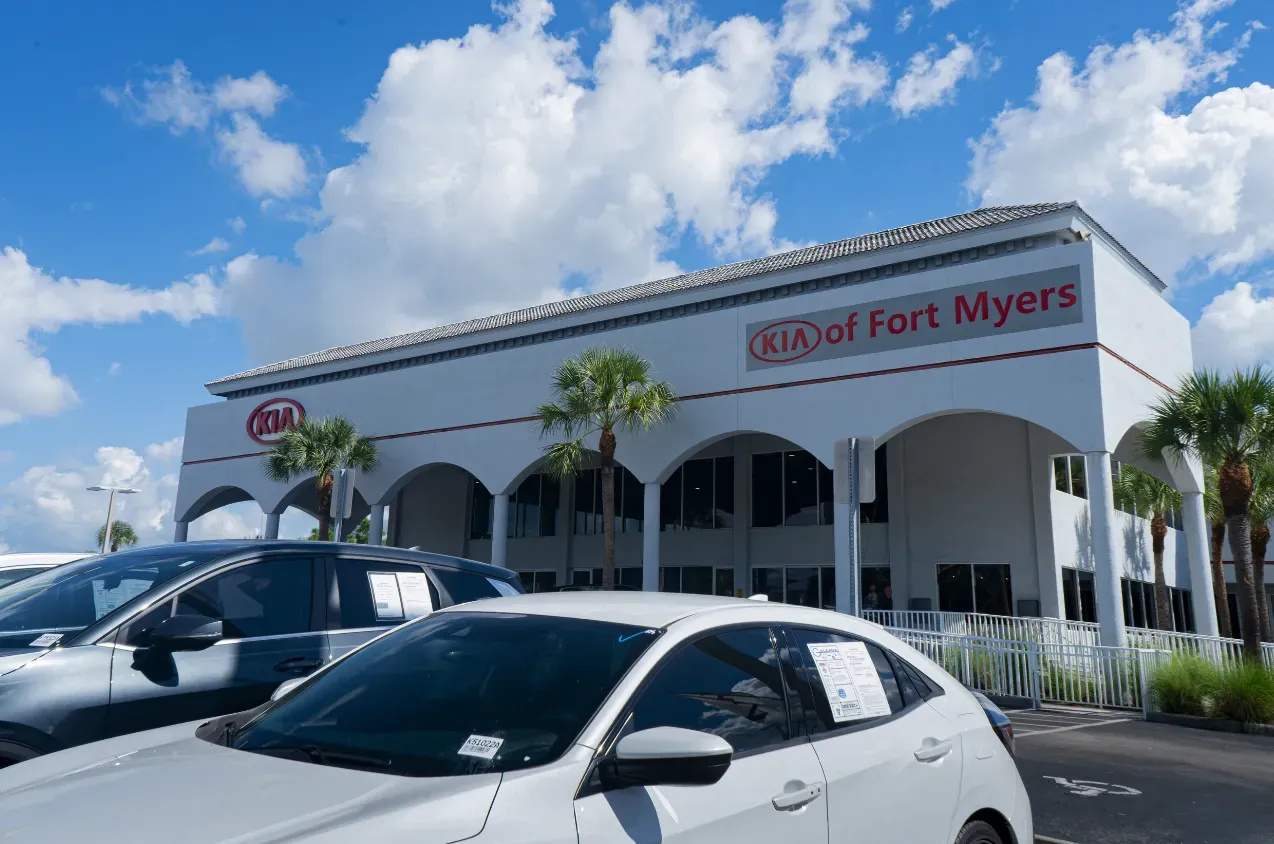
Browse inventory, book service, and apply for financing all in one place at Fort Myers Auto Group — home of CDJR of Fort Myers and Kia of Fort Myers, serving Fort Myers, Cape Coral, North Fort Myers, Lehigh Acres, Estero, and Bonita Springs, FL.
Key Takeaways
- Fort Myers Auto Group offers flexible car financing options including traditional loans and buy here pay here programs.
- Current new-car loan rates in Southwest Florida vary by lender and credit profile, while used-car loan rates also depend on these factors.
- In-house financing through the dealership eliminates back-and-forth between a sales desk and an outside bank.
- Trade-in equity reduces the amount financed instantly by lowering the principal balance before the first payment.
What car financing options are available near me?
Car buyers in Fort Myers encounter three primary financing paths: traditional loans from banks and credit unions, dealership in-house financing, and lease agreements. Each structure carries distinct approval criteria, payment schedules, and long-term cost implications that shape the total ownership expense.
Car Financing Options Near Me fall into categories that suit different credit profiles and budget priorities. Traditional loans, offered by local banks and credit unions throughout Lee County, provide a lump sum repaid over time with fixed or variable interest rates. These loans often reward strong credit scores with lower annual percentage rates. Leasing, by contrast, covers the vehicle's depreciation during a set term rather than its full purchase price. Monthly payments run lower than loan payments, though mileage caps and wear-and-tear fees apply at lease end.
In-house financing simplifies the process considerably. Fort Myers Auto Group specializes in new and used vehicle sales and financing for the local community. The company offers in-house financing that allows buyers to secure a loan directly through the dealership, often with more flexible terms than traditional lenders provide. This approach eliminates the back-and-forth between a sales desk and an outside bank.
How does buy here pay here financing work in Fort Myers?
Buy here pay here programs function as in-house auto loans where the dealership acts as the lender. Buyers who do not qualify for traditional financing can still obtain a vehicle and make payments directly to the dealership on a weekly or monthly schedule. Fort Myers Auto Group structures these arrangements to keep the transaction contained under one roof, from vehicle selection through final payment.
What should buyers compare when choosing a financing option?
Three factors deserve close scrutiny. The annual percentage rate determines total borrowing cost over the loan term. The payment frequency, whether monthly or weekly, affects household cash flow management. The down payment requirement varies by lender and vehicle type, shifting the upfront cash needed to drive off the lot. Buyers who weigh these elements against their income stability avoid committing to terms that strain monthly budgets.
How does dealership financing simplify buying?
Dealership financing consolidates the entire vehicle purchase into a single location. Buyers secure the car and the loan during one visit, eliminating the need to shuttle between a bank and a showroom.
Fort Myers Auto Group operates as a full-service dealer in Fort Myers, FL, specializing in new cars, used cars, service, and financing. This integrated model means a customer selects a vehicle and immediately sits down with a finance professional. The process removes the delay of waiting for an external bank's approval cycle. A buy here pay here dealership acts as the bank, approving and servicing the loan on site for quick decisions. The customer buys the car and pays the loan off at the same business, creating a direct, uncomplicated relationship.
What role does trade-in equity play in the finance package?
Trade-in equity reduces the amount financed instantly. Fort Myers Auto Group allows integration of trade-in equity directly into the finance package, streamlining the transaction. The value of the customer's current vehicle lowers the principal balance before the first payment is calculated. This streamlined trade-in approach turns a separate negotiation into a single, efficient step.
How do multi-lender networks improve loan terms?
A dealership with a broad lender network shops the application on the customer's behalf. Fort Myers Auto Group provides access to a network of multiple lenders, helping secure competitive rates. Instead of a buyer visiting several banks individually, the finance manager submits one application to various institutions. The result is a side-by-side comparison of offers without multiple credit inquiries spread over days. In-house financing through the dealership accommodates buyers with various credit backgrounds, offering flexible terms. Car Financing Options Near Me become far more accessible when a single point of contact manages the search for accessible financing and transparent pricing across different loan structures.
What are current car loan rates in Southwest Florida?
Current average rates for new-car loans in Southwest Florida vary by lender and credit profile. Used-car loans in the region also depend on these factors. These figures shift with economic indicators and lender policies, making trend monitoring essential for any buyer. A shopper who locks in a rate without comparing recent offers risks leaving hundreds of dollars in interest on the table over the life of the loan.
The gap between new and used rates reflects real-world lender calculations. New vehicles carry lower risk for lenders because they depreciate more predictably and serve as stronger collateral. A used car, already past its steepest depreciation curve, presents a different risk profile. That difference translates directly into the rate spread buyers see when browsing car financing options near me in Fort Myers.
Why does the APR matter more than the interest rate?
The annual percentage rate (APR) incorporates fees and gives a fuller picture of loan cost. Comparing nominal interest rates alone misses origination charges and other costs baked into the financing. An online loan calculator or amortization table helps translate APR and term into monthly payment and total interest paid, allowing side-by-side scenario comparisons that reveal the true cost of each offer.
How do new and used car loan rates compare?
New-car loans generally carry lower interest rates than used-car loans. Depreciation and lender risk drive this difference. A new vehicle holds its value in a way that reduces the lender's exposure, while a used vehicle's uncertain history and faster aging increase the perceived risk. For a Fort Myers buyer weighing a new model against a late-model used alternative, that rate spread becomes a key decision factor. The lower monthly payment on a used car can shrink or disappear once the higher APR is factored in.
Fort Myers Auto Group provides transparent pricing and accessible financing across its CDJR of Fort Myers and Kia of Fort Myers locations. The company's streamlined trade-in process helps Southwest Florida buyers apply equity directly toward their next purchase, reducing the amount financed and offsetting the impact of current rate levels.
How do credit profiles affect financing options?
Credit profiles directly shape the interest rates and loan terms available to car buyers in Fort Myers, Florida. Borrowers with excellent credit typically qualify for the lowest advertised rates on new and used car loans. A strong credit score signals lower risk to lenders, which translates into reduced monthly payments and lower total interest over the life of the loan.
What financing paths exist for buyers with bad credit?
Buyers with bad credit or limited credit history can still obtain financing through in-house programs at local dealerships. Buy Here Pay Here auto dealerships help customers get financed when traditional auto financing options are not available. These programs evaluate the buyer's current income and ability to pay rather than relying solely on a credit score.
Fort Myers Auto Group offers a range of financing solutions to accommodate diverse customer needs and budgets. The company connects customers with car financing options near me that match individual credit situations. Some dealerships feature a 99% approval rate and evaluate factors beyond just credit score when making decisions, according to DriveTime. This includes shoppers with bad credit or little to no credit history.
Can refinancing improve an existing auto loan?
Refinancing an existing auto loan may be an option for buyers who have improved their credit since the original purchase. A higher credit score often unlocks lower interest rates than the original loan carried. Fort Myers Auto Group assists customers in evaluating whether refinancing reduces their monthly payment or total interest cost.
| Credit Profile | Typical Financing Path | Key Consideration |
|---|---|---|
| Excellent credit | Traditional lender, lowest rates | Qualifies for advertised APRs |
| Fair credit | Traditional or in-house financing | Slightly higher rates apply |
| Bad or no credit | Buy Here Pay Here programs | Approval based on income, not score alone |
The credit tier a buyer occupies determines which financing route makes financial sense. Fort Myers Auto Group guides customers through these options without pressuring them into a single path.
What documents do I need to apply for a loan?
Loan applications require three core document categories. Proof of income, proof of residence, and current auto insurance information form the foundation of every approval package. Missing any single category stalls the process entirely.
Proof of income establishes repayment capacity. Recent pay stubs covering the last 30 days satisfy this requirement for salaried applicants. Self-employed buyers or those with variable income submit two years of tax returns instead. Lenders examine gross monthly income against existing debt obligations to calculate a debt-to-income ratio. This ratio directly determines the loan amount a buyer qualifies for in Fort Myers.
Proof of residence verifies a physical address within the lender's service area. A utility bill, lease agreement, or mortgage statement dated within 60 days serves this purpose. The document must display the applicant's name and current street address. Post office boxes do not qualify. Lenders in Southwest Florida use this verification to confirm local ties and stable housing.
Current auto insurance information must be presented before finalizing a vehicle loan. An insurance binder or declarations page showing coverage limits satisfies this requirement. Lenders mandate comprehensive and collision coverage for financed vehicles. Buyers who lack an existing policy secure a quote and binder before the loan closing.
What is the difference between pre-qualification and pre-approval?
Pre-qualification involves a soft credit check and provides an estimated loan amount. Pre-approval represents a conditional commitment from a lender after a hard credit inquiry. The distinction matters because pre-approval carries more weight with sellers and sets a firm budget before visiting dealerships like Fort Myers Auto Group.
How can buyers estimate monthly payments before applying?
Calculating monthly payments using an online loan calculator helps buyers compare different loan scenarios before applying. An amortization table translates APR and term into monthly payment and total interest paid. This step reveals the true cost difference between a 60-month and 72-month loan. Buyers who run these calculations arrive at the dealership with realistic expectations and avoid payment shock.
Should I lease or buy a car in Fort Myers?
The decision between leasing and buying in Fort Myers hinges on driving habits, ownership goals, and monthly budget tolerance. Leasing requires monthly payments for a set period, after which the vehicle is returned or purchased. Traditional auto loans result in ownership after the loan is paid off, with no mileage restrictions.
Car Financing Options Near Me in Fort Myers include both structures, and each carries distinct trade-offs. Leases often have lower monthly payments than comparable loans but include mileage and usage limits. Buyers who drive more than average or plan to keep the vehicle long-term typically benefit more from purchasing.
What are the main differences between leasing and buying?
| Factor | Leasing | Buying |
|---|---|---|
| Ownership | Returned or purchased at lease end | Full ownership after loan payoff |
| Monthly payment | Often lower | Typically higher |
| Mileage limits | Yes, usage restrictions apply | None |
| Long-term flexibility | Limited without purchase | Full control |
Fort Myers Auto Group offers both new and used vehicle inventory, enabling customers to explore purchase and lease options across multiple brands. The company operates CDJR of Fort Myers and Kia of Fort Myers, which gives Fort Myers buyers access to varied vehicle types under one ownership structure.
Which option costs less over time?
Total cost over the term matters more than the monthly payment alone. A lease may look cheaper month to month, but returning the vehicle means no equity accumulates. A traditional loan builds ownership value after the final payment. Buyers should evaluate each option against their financial situation and expected annual mileage before committing.
How can I compare loan terms and total cost?
Comparing loan terms requires looking beyond the monthly payment. The annual percentage rate (APR) provides a fuller picture of loan cost because APR incorporates fees that a nominal interest rate hides. Fort Myers buyers who compare only the stated rate risk underestimating the true expense of financing a vehicle in Southwest Florida.
An amortization table or online loan calculator translates APR and term into two critical figures: monthly payment and total interest paid. Running these calculations side by side reveals how a lower monthly payment often masks a longer term and higher overall interest. A 72-month loan carries a smaller payment than a 60-month loan, but the total interest climbs substantially.
What is the difference between APR and interest rate?
APR includes lender fees and other charges. The nominal interest rate excludes those costs. Comparing APR across lenders gives a more accurate basis for decision-making.
How does trade-in value affect the loan amount?
A streamlined trade-in reduces the financed principal. Lower principal means a smaller monthly payment and less total interest over the life of the loan. Fort Myers Auto Group integrates trade-in equity directly into the financing calculation.
| Comparison Factor | What to Evaluate |
|---|---|
| APR | Includes fees; use for lender comparison |
| Loan term | Longer term lowers payment but raises total interest |
| Trade-in equity | Reduces principal and monthly payment |
| Total interest paid | The true cost over the full loan life |
Fort Myers Auto Group's service centers provide ongoing vehicle care through certified technicians. Maintenance costs factor into long-term ownership expense, so buyers evaluating car financing options near me should account for service accessibility when choosing a dealership partner.
What steps should I take to get financed today?
Financing a vehicle in Fort Myers starts with reviewing current interest rates, loan terms, and total cost of ownership for the desired vehicle. Buyers who skip this step often carry higher monthly payments than necessary. A clear budget prevents that loss.
Car Financing Options Near Me begin with preparation. Fort Myers Auto Group offers a wide selection of new, used, and certified pre-owned vehicles to match any financing plan. That inventory breadth matters when loan terms depend on vehicle age and condition.
What should a buyer review before applying?
A buyer should review three figures before submitting any application. First, the interest rate determines monthly cost. Second, the loan term shapes total interest paid. Third, total cost of ownership includes insurance, fuel, and maintenance beyond the payment itself.
How does the online application work?
Completing an online application at a local dealership begins the approval process from home. The application captures income, employment, and credit details. Approval decisions follow without requiring an initial showroom visit.
After the online step, scheduling a dealership consultation reviews the credit profile, trade-in value, and available finance packages in person. A streamlined trade-in process converts an existing vehicle into down payment equity. Fort Myers Auto Group serves residents across eight communities, including Cape Coral, Naples, Estero, and Lehigh Acres, so consultation access spans Southwest Florida.
The sequence matters:
- Review rates and total ownership cost.
- Submit the online application.
- Schedule the in-person consultation.
- Finalize terms and take delivery.
Skipping the consultation leaves trade-in value unclaimed. Buyers who complete all four steps secure accessible financing with transparent pricing from a dealership group that operates locally.
FAQ
What car financing options are available near me in Fort Myers, FL?
Fort Myers Auto Group offers traditional loans, buy here pay here programs, and lease agreements for new and used vehicles.
How does buy here pay here financing work at Fort Myers Auto Group?
The dealership acts as the lender, allowing buyers to make weekly or monthly payments directly to Fort Myers Auto Group under one roof.
What should I compare when choosing a financing option?
Compare the annual percentage rate, payment frequency, and down payment requirement to match terms with your household cash flow.
Conclusion
Choosing between leasing and buying depends on your driving habits, budget, and long-term goals. Reviewing APR, loan term, and total interest paid ensures you select the option that fits your financial situation. Preparing your budget and trade-in value before applying streamlines the process. Completing the online application and in-person consultation secures transparent financing designed for your needs.
Our Fort Myers Showrooms
Fort Myers, FL 33912
Fort Myers, FL 33912